Beginning vs End-of-Month Contributions in an Investment Calculator
Learn why contribution timing changes a projection, how the calculation works, and how to compare tools using consistent assumptions.
Two investment calculators can use the same monthly contribution, annual return, and time horizon yet produce different balances. One common reason is whether each contribution is added at the beginning or the end of its period.
The difference is not an extra fee or a different return assumption. A beginning-of-month contribution simply spends more time inside the model than an otherwise identical end-of-month contribution.
Annuity due and ordinary annuity
End-of-period contributions follow the pattern often called an ordinary annuity. Beginning-of-period contributions follow an annuity-due pattern. Each beginning contribution receives one additional period of modeled growth.
For a periodic rate r, contribution P, and number of payments n, the
simplified future value of end-of-period contributions is:
P × (((1 + r)^n − 1) ÷ r)
For beginning-of-period contributions, multiply that result by (1 + r).
That closed-form formula assumes the contribution and compounding periods are aligned. The public calculator fixes contributions at the beginning of each selected period and compounds annually. Its shared engine also produces the separate beginning-versus-end comparison below. It places cash flows and compounding events on a shared timeline, so comparisons should use the same settings throughout.
A reproducible comparison using the shared engine
The following results use:
- $0 starting balance;
- $500 monthly contribution;
- fixed 6% annual return;
- annual compounding;
- no fee or inflation adjustment;
- either beginning- or end-of-month contributions.
| Time horizon | Total contributed | Beginning of month | End of month | Timing difference |
|---|---|---|---|---|
| 10 years | $60,000 | $81,655 | $81,260 | $395 |
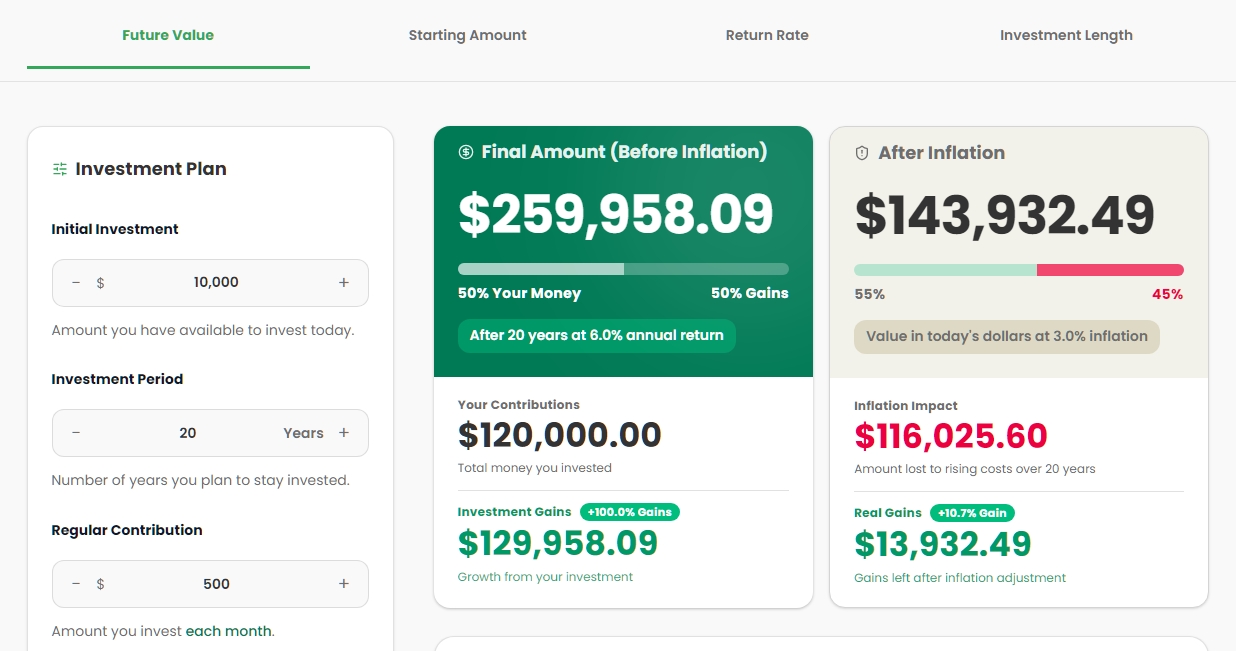
| 20 years | $120,000 | $227,887 | $226,783 | $1,104 |
| 30 years | $180,000 | $489,765 | $487,394 | $2,371 |
The table was generated with the same calculation engine used by the site. To reproduce it, open the monthly investment calculator, enter $0 starting balance, $500 per month, and 6%. The calculator reproduces the beginning-of-month column because timing and annual compounding are fixed. The end-of-month column is a separate worked example in that page’s timing table; there is no timing or compounding selector.
The results are rounded to the nearest dollar. A calculator using a different periodic-rate conversion or monthly compounding can produce different values without either implementation necessarily containing an arithmetic error.
Why the difference grows
One extra month of modeled growth is small for a single deposit. Repeating the timing difference for many years increases the cumulative gap. The size of that gap depends on:
- the assumed return;
- the contribution amount;
- the number of contributions;
- the compounding convention;
- whether cash flows are applied before or after a growth event.
The model does not imply that a beginning-of-month payment receives a positive return in every real month. It applies one deterministic fixed-return schedule. Actual market returns vary and may be negative during either part of a month.
Why another calculator may disagree
Before comparing results, check all of these settings:
| Setting | Possible implementations |
|---|---|
| Contribution date | First day, last day, or a fixed day during the month |
| Periodic return | Annual rate divided by 12 or converted to an equivalent monthly rate |
| Compounding | Annual, monthly, daily, or cash-flow-weighted approximation |
| First payment | Immediately or one full period after the start date |
| Final payment | Before or after the last growth calculation |
| Rounding | Every period or only at the final output |
Aligning only the annual percentage is not enough. The cash-flow timing and periodic-rate convention must also match.
The Investor.gov compound interest calculator can provide a separate reference for contribution scenarios, but its available timing controls and conventions should be checked before treating a difference as an error.
Practical interpretation
Use the timing that best represents the cash flow being modeled. A salary-based contribution might arrive after payday. An automated transfer could occur on the first day of a month. Neither label is universally correct.
For planning comparisons:
- Record the timing convention; this site’s calculator fixes it at the beginning of each contribution period.
- Keep that timing unchanged across the lower and higher return cases.
- Compare total contributions separately from investment gains.
- Record the convention when sharing a result.
The full calculation methodology explains how the engine handles cash flows and compounding. These worked outputs are hypothetical, exclude taxes, fees, and actual market volatility unless represented in the inputs, and are not financial advice.
More Posts
Why S&P 500 Calculators Give Different Results
Learn why S&P 500 calculations differ when tools use different dividend, contribution timing, compounding, fee, tax, inflation, and return assumptions.
How to Choose a Return Assumption for an S&P 500 Calculator
A practical framework for testing conservative, central, and higher return assumptions without treating a calculator as a forecast.
Lump Sum vs Dollar-Cost Averaging: What a Fixed-Return Model Shows
Compare investing a lump sum immediately with spreading it over time, including what fixed-return calculations can and cannot tell you.